Installment Sale Definitions
Five terms, each defined in about 40 words, with the rule, the source and a link to the full guide.
By Hans Goldstein (Enrolled Agent, admitted to practice before the IRS) · Updated
Plain definitions of the terms sellers and advisors search for, each in about 40 words, each with a link to the full guide, the rule table, a worked example and primary sources. Numbers that change every year or every month are on the rates and thresholds tables, with a downloadable CSV.
Section 453A interest charge
The Section 453A interest charge is interest added to your tax when installment notes from sales over $150,000 total more than $5 million at year end. It is figured on the deferred tax tied to the face above $5 million, at the IRS underpayment rate.
Installment sale vs 1031 exchange
An installment sale reports gain as the buyer pays principal (Section 453, Form 6252) and lets you leave real estate. A 1031 exchange postpones all gain if you reinvest all proceeds in like-kind real property within 180 days (Section 1031, Form 8824). They can be combined on boot.
Depreciation recapture in an installment sale
Depreciation recapture in an installment sale is the ordinary income from Section 1245 or 1250 depreciation, which Section 453(i) taxes in the year of sale even if no payment arrives that year. The rest of the gain is reported as payments are received.
Read the full guide: Depreciation recapture in an installment sale
Contingent payment sale
A contingent payment sale is an installment sale where the total price cannot be fixed by the end of the year of sale, such as an earn-out. It can still use the installment method, with basis recovered under Temporary Regulation 15a.453-1(c).
The key rules in one table
As of November 14, 2026.
| Term | Key number or rule | Source |
|---|---|---|
| Section 453A interest charge | Sales price over $150,000; year-end note face over $5,000,000; underpayment rate 7% for the quarter beginning October 1, 2026 | IRC 453A; Rev. Rul. 2026-15 |
| Installment sale vs 1031 exchange | 1031: identify within 45 days, close within 180 days, real property only. Installment sale: Form 6252, recapture taxed in year one | IRC 1031(a); IRC 453(i) |
| Related-party sale | Buyer resells within 2 years: you are treated as paid | IRC 453(e) |
How to cite
Goldstein, Hans. "Installment sale definitions." Big Sale Tax (Hans Goldstein: Tax & Exit Planning). Updated November 14, 2026. https://bigsaletax.com/definitions/
Frequently asked questions
What is the Section 453A interest charge?
What is the difference between an installment sale and a 1031 exchange?
How is depreciation recapture taxed in an installment sale?
What is a contingent payment sale?
What is a related-party installment sale?
Hans Goldstein is an Enrolled Agent, admitted to practice before the Internal Revenue Service. Not affiliated with or endorsed by the IRS. General education, not tax or legal advice for your situation.
Also free: the book Same Sale, Different Tax, the same $1,000,000 gain taxed ten ways. Want it run on your sale? Book a free scope call to see whether the Big Sale Tax Analysis is worth it.
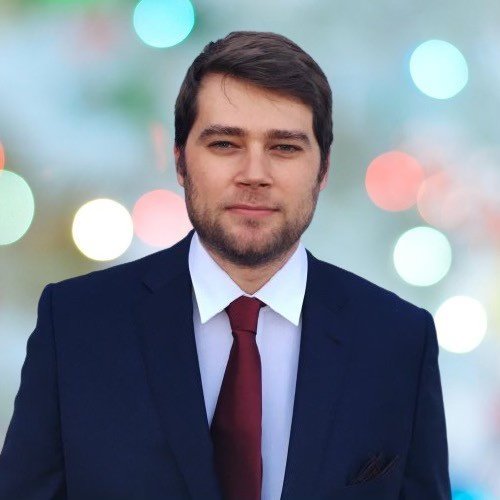
Who you will talk to
Hans Goldstein · Sacramento, California
Hans Goldstein: Tax & Exit Planning, an independent practice. Enrolled Agent, admitted to practice before the Internal Revenue Service. CA Insurance License #4273294, NPN 20602398.
- What happens first
- You fill in the short form for a free scope call, about 5 minutes. Hans reviews every one personally and replies within 1 business day. If it is a fit, you get a link to book the call.
- The scope call
- Fifteen minutes, free: price, timeline, what you are selling and what the money is for. Scope means you hear whether the analysis is worth it for your sale.
- What you get
- A written side-by-side comparison of your cash-sale baseline against every path that fits, year-by-year numbers, a written recommendation, and a review meeting with you and, if you like, your CPA and attorney.
- What it costs
- The scope call is free. The Big Sale Tax Analysis is $5,000 per household per transaction, only if you decide it is worth it. No retainer, no hourly billing, no obligation to use any strategy.
- How Hans is paid
- The $5,000 fee pays for analysis only and is not reduced or credited if you buy anything. You are never required to buy anything. No referral fees are paid to or received from brokers, CPAs or attorneys. Hans is also a licensed insurance producer with a separately owned insurance business. That business is not part of this engagement, and the analysis does not recommend insurance products. If you later choose an installment sale funded through an insurance company, that company pays Hans a commission through his separate insurance business. He may be compensated by that business if you use an insurance-funded installment sale. Hans is an Enrolled Agent (EA), admitted to practice before the Internal Revenue Service. He is not a CPA, attorney or registered investment adviser; the analysis models tax effects and does not recommend specific securities. Read the disclosures.
Book a free scope call or call 213-340-2018. Hans answers or calls back the same business day.