Installment Sale Rates and Thresholds
AFR by month, the 453A threshold and underpayment rate, and the 2026 capital gains and NIIT thresholds. Dated, sourced to the IRS, with CSV downloads.
By Hans Goldstein (Enrolled Agent, admitted to practice before the IRS) · Updated
Download (CC BY 4.0): AFR monthly CSV · underpayment rate CSV · thresholds CSV. Use freely with credit; see how to cite at the bottom.
Applicable federal rates (AFR) by month, January 2023 to November 2026
Table 1 of each monthly Revenue Ruling, annual compounding. Short-term: notes of 3 years or less. Mid-term: over 3 up to 9 years. Long-term: over 9 years. Seller notes are tested against the AFR under IRC 1274(d); see installment sale interest and the AFR.
| Month | Short-term | Mid-term | Long-term | Source |
|---|---|---|---|---|
| November 2026 | 4.67% | 5.08% | 5.52% | Rev. Rul. 2026-21 |
| October 2026 | 4.25% | 4.61% | 5.22% | Rev. Rul. 2026-19 |
| September 2026 | 4.18% | 4.49% | 5.12% | Rev. Rul. 2026-17 |
| August 2026 | 4.10% | 4.35% | 4.92% | Rev. Rul. 2026-13 |
| July 2026 | 4.00% | 4.35% | 4.98% | Rev. Rul. 2026-12 |
| June 2026 | 3.85% | 4.13% | 4.87% | Rev. Rul. 2026-11 |
| May 2026 | 3.82% | 4.08% | 4.83% | Rev. Rul. 2026-9 |
| April 2026 | 3.59% | 3.82% | 4.62% | Rev. Rul. 2026-7 |
| March 2026 | 3.59% | 3.93% | 4.72% | Rev. Rul. 2026-6 |
| February 2026 | 3.56% | 3.86% | 4.70% | Rev. Rul. 2026-3 |
| January 2026 | 3.63% | 3.81% | 4.63% | Rev. Rul. 2026-2 |
| December 2025 | 3.66% | 3.79% | 4.55% | Rev. Rul. 2025-24 |
| November 2025 | 3.69% | 3.83% | 4.62% | Rev. Rul. 2025-21 |
| October 2025 | 3.81% | 3.87% | 4.73% | Rev. Rul. 2025-19 |
| September 2025 | 4.00% | 4.04% | 4.83% | Rev. Rul. 2025-17 |
| August 2025 | 4.03% | 4.06% | 4.82% | Rev. Rul. 2025-14 |
| July 2025 | 4.12% | 4.19% | 4.90% | Rev. Rul. 2025-13 |
| June 2025 | 4.00% | 4.07% | 4.77% | Rev. Rul. 2025-12 |
| May 2025 | 4.05% | 4.10% | 4.62% | Rev. Rul. 2025-10 |
| April 2025 | 4.16% | 4.21% | 4.61% | Rev. Rul. 2025-8 |
| March 2025 | 4.31% | 4.46% | 4.82% | Rev. Rul. 2025-6 |
| February 2025 | 4.34% | 4.52% | 4.86% | Rev. Rul. 2025-5 |
| January 2025 | 4.33% | 4.24% | 4.53% | Rev. Rul. 2025-1 |
| December 2024 | 4.30% | 4.18% | 4.53% | Rev. Rul. 2024-26 |
| November 2024 | 4.00% | 3.70% | 4.15% | Rev. Rul. 2024-24 |
| October 2024 | 4.21% | 3.70% | 4.10% | Rev. Rul. 2024-21 |
| September 2024 | 4.57% | 4.02% | 4.37% | Rev. Rul. 2024-17 |
| August 2024 | 4.95% | 4.34% | 4.52% | Rev. Rul. 2024-15 |
| July 2024 | 5.06% | 4.49% | 4.61% | Rev. Rul. 2024-13 |
| June 2024 | 5.12% | 4.66% | 4.79% | Rev. Rul. 2024-12 |
| May 2024 | 4.97% | 4.42% | 4.55% | Rev. Rul. 2024-9 |
| April 2024 | 4.89% | 4.30% | 4.45% | Rev. Rul. 2024-7 |
| March 2024 | 4.71% | 4.13% | 4.40% | Rev. Rul. 2024-4 |
| February 2024 | 4.68% | 3.98% | 4.18% | Rev. Rul. 2024-3 |
| January 2024 | 5.00% | 4.37% | 4.54% | Rev. Rul. 2024-2 |
| December 2023 | 5.26% | 4.82% | 5.03% | Rev. Rul. 2023-21 |
| November 2023 | 5.30% | 4.69% | 4.83% | Rev. Rul. 2023-20 |
| October 2023 | 5.22% | 4.43% | 4.46% | Rev. Rul. 2023-18 |
| September 2023 | 5.12% | 4.19% | 4.19% | Rev. Rul. 2023-16 |
| August 2023 | 5.07% | 4.09% | 4.03% | Rev. Rul. 2023-13 |
| July 2023 | 4.80% | 3.85% | 3.98% | Rev. Rul. 2023-12 |
| June 2023 | 4.43% | 3.56% | 3.79% | Rev. Rul. 2023-10 |
| May 2023 | 4.30% | 3.57% | 3.72% | Rev. Rul. 2023-9 |
| April 2023 | 4.86% | 4.15% | 4.02% | Rev. Rul. 2023-6 |
| March 2023 | 4.50% | 3.70% | 3.74% | Rev. Rul. 2023-5 |
| February 2023 | 4.47% | 3.82% | 3.86% | Rev. Rul. 2023-3 |
| January 2023 | 4.50% | 3.85% | 3.84% | Rev. Rul. 2023-1 |
Section 453A: the $5 million threshold and the underpayment rate
The 453A interest charge applies to an installment obligation from a sale with a sales price over $150,000, when the face amount of all such obligations that arose in the year and are outstanding at year end exceeds $5,000,000 (IRC 453A(b)). Neither dollar figure is indexed for inflation. The rate is the IRC 6621(a)(2) underpayment rate: the federal short-term rate plus 3 percentage points, reset each quarter. Definition and formula: 453A interest charge.
| Quarter | Underpayment rate | Source |
|---|---|---|
| 2026 Q4 | 7% | Rev. Rul. 2026-15 |
| 2026 Q3 | 7% | IRB 2026-22 |
| 2026 Q2 | 6% | IRB 2026-8 |
| 2026 Q1 | 7% | Rev. Rul. 2025-22 |
| 2025 Q4 | 7% | Rev. Rul. 2025-18 |
| 2025 Q3 | 7% | Rev. Rul. 2025-11 |
| 2025 Q2 | 7% | Rev. Rul. 2025-7 |
| 2025 Q1 | 7% | Rev. Rul. 2024-25 |
| 2024 Q4 | 8% | Rev. Rul. 2024-18 |
| 2024 Q3 | 8% | Rev. Rul. 2024-11 |
| 2024 Q2 | 8% | Rev. Rul. 2024-6 |
| 2024 Q1 | 8% | Rev. Rul. 2023-22 |
| 2023 Q4 | 8% | Rev. Rul. 2023-17 |
| 2023 Q3 | 7% | Rev. Rul. 2023-11 |
| 2023 Q2 | 7% | Rev. Rul. 2023-4 |
| 2023 Q1 | 7% | IRB 2022-51 |
2026 capital gains rates, brackets and NIIT thresholds
Taxable-income thresholds for the 0% and 15% long-term capital gains rates apply for tax years beginning in 2026; above the 15% figure the rate is 20%. Unrecaptured Section 1250 gain is taxed at up to 25%. The NIIT thresholds are set in the statute and are not indexed.
| Item | Value | Source |
|---|---|---|
| 453A: minimum sales price | $150,000 | IRC 453A(b)(1) |
| 453A: year-end note face threshold | $5,000,000 (exactly $5,000,000 does not trigger) | IRC 453A(b)(2) |
| 2026 LTCG 0% rate top, joint and surviving spouse | $98,900 | Rev. Proc. 2025-32, sec. 4.03 |
| 2026 LTCG 15% rate top, joint and surviving spouse | $613,700 | Rev. Proc. 2025-32, sec. 4.03 |
| 2026 LTCG 0% rate top, single | $49,450 | Rev. Proc. 2025-32, sec. 4.03 |
| 2026 LTCG 15% rate top, single | $545,500 | Rev. Proc. 2025-32, sec. 4.03 |
| 2026 LTCG 0% rate top, married filing separately | $49,450 | Rev. Proc. 2025-32, sec. 4.03 |
| 2026 LTCG 15% rate top, married filing separately | $306,850 | Rev. Proc. 2025-32, sec. 4.03 |
| 2026 LTCG 0% rate top, head of household | $66,200 | Rev. Proc. 2025-32, sec. 4.03 |
| 2026 LTCG 15% rate top, head of household | $579,600 | Rev. Proc. 2025-32, sec. 4.03 |
| 2026 LTCG 0% rate top, estates and trusts | $3,300 | Rev. Proc. 2025-32, sec. 4.03 |
| 2026 LTCG 15% rate top, estates and trusts | $16,250 | Rev. Proc. 2025-32, sec. 4.03 |
| NIIT rate | 3.8% | IRC 1411(a) |
| NIIT threshold (MAGI), joint and surviving spouse | $250,000 | IRC 1411(b) |
| NIIT threshold (MAGI), single and head of household | $200,000 | IRC 1411(b) |
| NIIT threshold (MAGI), married filing separately | $125,000 | IRC 1411(b) |
2027 figures
Not yet published. As of November 14, 2026 the IRS had not released the 2027 inflation adjustments (the annual Revenue Procedure that follows the 2026 one, Rev. Proc. 2025-32). Checked: IRS news releases through IR-2026-122 (October 14, 2026) and the IRS Revenue Procedure listing through Rev. Proc. 2026-32. This page adds the 2027 rows the day the IRS publishes them. The $150,000 and $5,000,000 figures in 453A and the NIIT thresholds do not change with inflation.
Using the tables: two dated examples
Lowest-of-3-months AFR. A seller signs a binding written contract in November 2026 for a note with a 6-year weighted average maturity (mid-term class, over 3 and up to 9 years). IRC 1274(d)(2) lets the seller use the lowest mid-term AFR in the three months ending with the contract month: September 4.49%, October 4.61%, November 5.08%. The lowest is 4.49% (September 2026, Rev. Rul. 2026-17). The note must carry at least that rate or part of the price is recharacterized as interest.
Section 453A interest. A calendar-year seller holds an $8,000,000 note from a 2026 sale and has $1,200,000 of deferred tax at year end 2026. Applicable percentage = ($8,000,000 minus $5,000,000) divided by $8,000,000 = 37.5%. The rate for the quarter containing December 2026 is 7% (Rev. Rul. 2026-15). Interest = $1,200,000 x 37.5% x 7% = $31,500. The method and a full ten-year schedule are on the 453A interest charge guide.
How to cite
Goldstein, Hans. "Installment sale rates and thresholds: AFR, 453A and 2026 capital gains tables." Big Sale Tax (Hans Goldstein: Tax & Exit Planning). Updated November 14, 2026. https://bigsaletax.com/tax-tables/ . Data licensed CC BY 4.0.
Method: every AFR and underpayment figure is read from the IRS Revenue Ruling named in its row (rr-YY-NN.pdf on irs.gov); a quarter whose ruling is not at that address is read from the IRS quarterly interest rates page and labeled with the Internal Revenue Bulletin it cites. The rebuild script is public: ask Hans for it. Education only; confirm the rate for your contract month against the ruling before you sign a note.
Frequently asked questions
What is the AFR for November 2026?
What is the Section 453A underpayment rate?
What is the Section 453A threshold?
When do the 2027 capital gains thresholds come out?
Hans Goldstein is an Enrolled Agent, admitted to practice before the Internal Revenue Service. Not affiliated with or endorsed by the IRS. General education, not tax or legal advice for your situation.
Also free: the book Same Sale, Different Tax, the same $1,000,000 gain taxed ten ways. Want it run on your sale? Book a free scope call to see whether the Big Sale Tax Analysis is worth it.
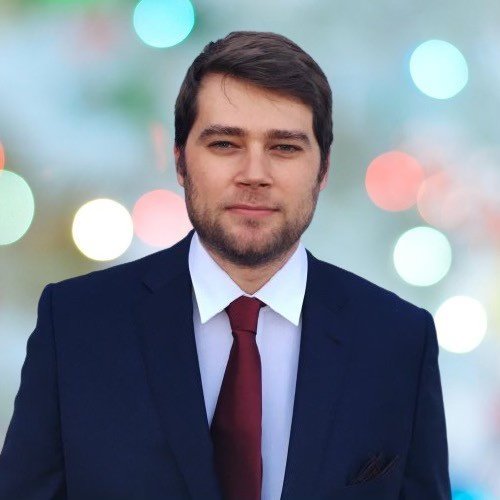
Who you will talk to
Hans Goldstein · Sacramento, California
Hans Goldstein: Tax & Exit Planning, an independent practice. Enrolled Agent, admitted to practice before the Internal Revenue Service. CA Insurance License #4273294, NPN 20602398.
- What happens first
- You fill in the short form for a free scope call, about 5 minutes. Hans reviews every one personally and replies within 1 business day. If it is a fit, you get a link to book the call.
- The scope call
- Fifteen minutes, free: price, timeline, what you are selling and what the money is for. Scope means you hear whether the analysis is worth it for your sale.
- What you get
- A written side-by-side comparison of your cash-sale baseline against every path that fits, year-by-year numbers, a written recommendation, and a review meeting with you and, if you like, your CPA and attorney.
- What it costs
- The scope call is free. The Big Sale Tax Analysis is $5,000 per household per transaction, only if you decide it is worth it. No retainer, no hourly billing, no obligation to use any strategy.
- How Hans is paid
- The $5,000 fee pays for analysis only and is not reduced or credited if you buy anything. You are never required to buy anything. No referral fees are paid to or received from brokers, CPAs or attorneys. Hans is also a licensed insurance producer with a separately owned insurance business. That business is not part of this engagement, and the analysis does not recommend insurance products. If you later choose an installment sale funded through an insurance company, that company pays Hans a commission through his separate insurance business. He may be compensated by that business if you use an insurance-funded installment sale. Hans is an Enrolled Agent (EA), admitted to practice before the Internal Revenue Service. He is not a CPA, attorney or registered investment adviser; the analysis models tax effects and does not recommend specific securities. Read the disclosures.
Book a free scope call or call 213-340-2018. Hans answers or calls back the same business day.