Should you set up an ILIT after selling property?
After a big sale, an irrevocable life insurance trust can own a policy whose death benefit pays the estate tax on the proceeds, outside your taxable estate, so heirs do not lose 40% of the amount over the $15,000,000 exemption.
It only helps if the estate is over or growing toward the exemption, and the trust must buy the policy (or you must live 3 years after transferring an existing one).
By Hans Goldstein, Enrolled Agent, admitted to practice before the IRS · Updated
Short answer: only if the sale leaves you over, or on track to grow over, $15,000,000 ($30,000,000 for a couple). Below that line the trust buys protection you do not need.
Who needs it after a sale
Before the sale, real estate or a business held until death would get a step-up (IRC 1014) and the estate tax was a problem for later. After the sale, the estate is cash and notes, it grows, and the exemption only grows with inflation. The ILIT question is: how big will the estate be when you die, and who pays 40% on the amount over the line?
| Age at death | Estate (4.8% net growth) | Exemption | Federal estate tax | Heirs keep, no ILIT | Death benefit the ILIT needs |
|---|---|---|---|---|---|
| 70 | $17,000,000 | $15,000,000 | $800,000 | $16,200,000 | $800,000 |
| 79 | $25,923,908 | $18,840,000 | $2,833,563 | $23,090,345 | $2,833,563 |
| 84 | $32,772,297 | $21,310,000 | $4,584,919 | $28,187,378 | $4,584,919 |
| 89 | $41,429,843 | $24,110,000 | $6,927,937 | $34,501,906 | $6,927,937 |
The tax due at 70 is $800,000. At 84 it is $4,584,919, at 89 $6,927,937, because the estate grows faster than the indexed exemption. A policy owned by the trust, with a death benefit sized to that tax, lets the heirs pay it without selling assets. The death benefit is outside the estate because the trust, not you, owns the policy (IRC 2042).
The cost: every premium you give the trust leaves your estate as a gift. Gifts under the $19,000 annual exclusion per beneficiary use no exemption; larger premiums use some of it. Premiums depend on age, health and the policy design, so this page shows the tax the policy must cover, not a premium.
Estate figures are from the Big Sale Tax estate engine: federal estate tax at 40% over the basic exclusion amount, $15,000,000 in 2026 and $15,460,000 in 2027, then indexed at an assumed 2.5% a year and rounded to $10,000 as IRC 2010(c)(3) requires. Assets grow 6% a year less a 20% tax drag (4.8% net). No state estate tax. Illustration only.
How to fund premiums from the sale
- Annual exclusion gifts. $19,000 per beneficiary per year in 2026 ($38,000 from a couple), sent to the trust. The trustee sends each beneficiary a Crummey notice of a short right to withdraw, which makes the gift a present interest (IRC 2503(b)).
- From installment payments. An installment or structured installment sale pays you on a schedule; part of each payment can fund the premium, so the policy is paid from money that arrives over time.
- Larger premiums. A lump gift that uses part of the exemption, or split-dollar arrangements where you or a family entity advance premiums and are repaid at death. These need a tax attorney.
The 3-year rule
If you give an existing policy to the trust and die within three years, the death benefit is pulled back into your estate (IRC 2035). The clean way is for the trustee to apply for and own the new policy from day one, with you giving cash for the premiums.
Gray area
Second-to-die or single life?
- Position A. For a married couple using the unlimited marital deduction and portability, the tax is due at the second death, so a survivorship policy that pays then is the natural fit and usually costs less.
- Position B. If one spouse is much older or uninsurable, or the estate is over the line at the first death because portability was not elected, single-life coverage on the insurable spouse can fit better.
What both sides agree on: Match the policy to when the tax is actually due.
Is the insurance worth more than the tax it covers?
- Position A. Paying premiums with dollars that would otherwise be taxed at 40% in the estate makes even a modest policy return worth it.
- Position B. If you die young the policy wins big; if you live past 95 the total premiums can approach the death benefit, and investing the premiums might have done as well.
What both sides agree on: Run it at several death ages, which is what the estate tax strategy calculator does.
When not to do it
- The estate is and will stay under the exemption.
- You are uninsurable or the premium is out of proportion to the tax.
- You need the money: an ILIT is irrevocable and the gifts are gone.
- A state estate tax is the only problem and a move would fix it more cheaply.
See also estate tax exemption 2026, buy, borrow, die vs 1031 + installment sale + ILIT and installment sale to an intentionally defective grantor trust.
Related guides: structured installment sale, estate tax exemption 2026, selling a business before retirement.
Frequently asked questions
What is an ILIT?
An irrevocable trust that owns life insurance on your life. Because the trust owns the policy, the death benefit is not in your taxable estate (IRC 2042), and the trustee can use it to buy assets from the estate or lend to it so the estate tax gets paid.
Can I move my existing policy into an ILIT?
Yes, but if you die within three years of the transfer the death benefit is included in your estate (IRC 2035). A new policy applied for by the trustee avoids that.
Do I need an ILIT if my estate is under $15,000,000?
Usually not for federal estate tax. Check whether growth will carry it over the line, and whether your state has its own estate tax with a lower exemption.
What is a Crummey notice?
A letter telling each beneficiary they may withdraw the gift you just made to the trust for a short time, usually 30 days. That right makes the gift qualify for the $19,000 annual exclusion.
Can sale proceeds pay the premiums?
Yes. You give cash to the trust and the trustee pays the premium. The gifts reduce your estate as they go.
Sources
- IRC 2042, life insurance proceeds in the gross estate (Cornell LII)
- IRC 2035, transfers within three years of death (Cornell LII)
- IRC 2503(b), annual gift exclusion (Cornell LII)
- IRC 2010, unified credit and basic exclusion amount (Cornell LII)
- IRC 2001, estate tax rate schedule (Cornell LII)
- IRS, What's new: estate and gift tax
- IRS Rev. Proc. 2025-32, 2026 inflation adjustments
- IRS Instructions for Form 709, gift tax return
- IRC 1014, basis of property acquired from a decedent (Cornell LII)
- IRC 691, income in respect of a decedent (Cornell LII)
Links checked October 30, 2026.
Hans Goldstein is an Enrolled Agent, admitted to practice before the Internal Revenue Service. Not affiliated with or endorsed by the IRS. General education, not tax or legal advice for your situation.
Insurance products offered through Goldstein & Co. LLC dba Goldstein Insurance Services, CA license 4273294. If you implement a structured installment sale through that business, Hans is paid a commission by the insurer; it is built into the payout rate. See the disclosures.
Also free: the book Same Sale, Different Tax, the same $1,000,000 gain taxed ten ways. Want it run on your sale? Book a free scope call to see whether the Big Sale Tax Analysis is worth it.
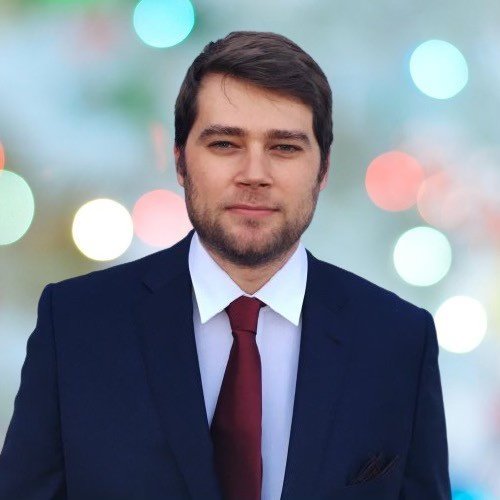
Who you will talk to
Hans Goldstein · Sacramento, California
Hans Goldstein: Tax & Exit Planning, an independent practice. Enrolled Agent, admitted to practice before the Internal Revenue Service. CA Insurance License #4273294, NPN 20602398.
- What happens first
- You fill in the short form for a free scope call, about 5 minutes. Hans reviews every one personally and replies within 1 business day. If it is a fit, you get a link to book the call.
- The scope call
- Fifteen minutes, free: price, timeline, what you are selling and what the money is for. Scope means you hear whether the analysis is worth it for your sale.
- What you get
- A written side-by-side comparison of your cash-sale baseline against every path that fits, year-by-year numbers, a written recommendation, and a review meeting with you and, if you like, your CPA and attorney.
- What it costs
- The scope call is free. The Big Sale Tax Analysis is $5,000 per household per transaction, only if you decide it is worth it. No retainer, no hourly billing, no obligation to use any strategy.
- How Hans is paid
- The $5,000 fee pays for analysis only and is not reduced or credited if you buy anything. You are never required to buy anything. No referral fees are paid to or received from brokers, CPAs or attorneys. Hans is also a licensed insurance producer with a separately owned insurance business. That business is not part of this engagement, and the analysis does not recommend insurance products. If you later choose an installment sale funded through an insurance company, that company pays Hans a commission through his separate insurance business. He may be compensated by that business if you use an insurance-funded installment sale. Hans is an Enrolled Agent (EA), admitted to practice before the Internal Revenue Service. He is not a CPA, attorney or registered investment adviser; the analysis models tax effects and does not recommend specific securities. Read the disclosures.
Book a free scope call or call 213-340-2018. Hans answers or calls back the same business day.
Does your sale need an ILIT?
Send the sale price and a rough picture of your other assets. On a free scope call we check the estate tax at several ages before anyone talks about a policy.
Prefer email? Request the analysis by email.
You talk to Hans Goldstein. Enrolled Agent, admitted to practice before the IRS.