What is a structured installment sale?
A structured installment sale is a Section 453 installment sale where the buyer's payment obligation is assigned to an assignment company that funds it with an annuity from a highly rated life insurer, so the seller gets a fixed schedule of payments instead of a buyer's note. Gain is taxed as each payment arrives, the same as any installment sale; what changes is who owes you the money.
By Hans Goldstein, Enrolled Agent, admitted to practice before the IRS · Updated
Short answer: same tax law as any installment sale (IRC 453), with a life insurer standing behind the payments instead of the buyer. On a $3,000,000 sale with a $600,000 basis in California, a cash sale adds $848,569 of tax at once; a 15-year structured sale adds $25,016 in year one and $615,022 on the gain over all 15 years.
How the money moves
- Before closing, the seller and buyer sign a purchase agreement that calls for deferred payments, and an assignment agreement.
- At closing, the buyer pays the full price. The part to be deferred goes to an assignment company, which takes over the buyer's duty to pay you.
- The assignment company buys an annuity from a life insurer to fund that duty. You are the payee, not the owner: you cannot cash it in, borrow against it or change it.
- You receive the payments on the agreed schedule (monthly, yearly, level, rising, a lump later). Each payment is part return of basis, part gain, part interest, reported on Form 6252.
The assignment step is borrowed from personal injury structured settlements (IRC 130), but a sale is not a settlement: the tax result comes from IRC 453, not 130. See the two kinds of installment sales for the seller-note version side by side.
Seller note vs structured installment sale vs 1031 vs Delaware statutory trust
| Seller note (buyer pays you) | Structured installment sale | 1031 exchange | Delaware statutory trust (via 1031) | |
|---|---|---|---|---|
| Who pays you | The buyer | An assignment company, funded by a life insurer | Nobody: you own new property | Trust sponsor distributes rent |
| Default risk | The buyer's business and credit | The insurer's claims-paying ability; state life and health insurance protection association limits behind it | Property and tenant risk | Sponsor, tenant and debt risk |
| Liquidity | Note can sometimes be sold, but selling or pledging it triggers tax | None: payments cannot be accelerated or sold | Sell the property (tax due unless you exchange again) | Low; sale at sponsor's timing |
| Tax timing | Gain as principal arrives (453) | Gain as principal arrives (453) | Deferred until you sell without exchanging | Deferred, same as a 1031 |
| Typical minimum | Any size | Often $100,000 or more of deferred amount | Replacement at least equal in value and debt | Often $100,000 |
| Fees | Legal drafting, servicing | Built into the payout rate | Intermediary, closing costs on the new property | Load and sponsor fees |
The tax rules that make or break it
- No control over the money. If you could take the cash at closing, you have constructive receipt (Treas. Reg. 1.451-2) and the whole gain is taxed now. The terms must be signed before you have a right to the funds, and you cannot have a right to accelerate, pledge or sell the payments (economic benefit).
- Pledge rule. Borrowing against an installment obligation is treated as a payment (IRC 453A(d)).
- Interest charge over $5,000,000. If deferred notes from sales over $150,000 total more than $5,000,000 at year end, a yearly interest charge applies on the deferred tax (IRC 453A). 453A interest charge calculator.
- What cannot use it. Inventory and dealer property (IRC 453(b)(2)) and publicly traded stock or securities (IRC 453(k)(2)).
- Recapture in year one. Section 1245 and 1250 ordinary-income recapture is taxed in the year of sale whatever the payments (IRC 453(i)). Unrecaptured 1250 gain on a building is spread and reported first (Treas. Reg. 1.453-12).
- At death. The unreported gain is income in respect of a decedent (IRC 691): the payments keep coming to your heirs, there is no step-up on that gain (IRC 1014(c)), and the remaining value counts in your estate.
Worked example: $3,000,000 sale, $600,000 basis, 15 years
Married couple in California with $150,000 of other income sells a business or land with no depreciation recapture for $3,000,000. Gain: $2,400,000. Option one, cash: $848,569 of tax in 2026 ($478,865 federal, $87,400 NIIT, $282,304 California), leaving $2,151,431. Option two, a 15-year structured installment sale at 6%: $308,888 a year, $4,633,324 in all.
| Year | Payment | Gain reported | Tax on the gain | Tax on the interest |
|---|---|---|---|---|
| 1 | $308,888 | $103,111 | $25,016 | $64,908 |
| 2 | $308,888 | $109,297 | $26,754 | $62,039 |
| 5 | $308,888 | $130,175 | $32,621 | $52,357 |
| 10 | $308,888 | $174,203 | $44,993 | $31,988 |
| 15 | $308,888 | $233,123 | $61,549 | $6,137 |
| All 15 years | $4,633,324 | $2,400,000 | $615,022 | $582,427 |
The after-tax gap at the same rate. Give both sides the same 6% return and tax all the interest every year: after 15 years the cash seller has $3,918,811 and the structured-sale seller $4,493,632, a $574,821 difference ($320,328 in today's dollars). The reason is simple: the tax that would have left in year one keeps earning until it is due.
Tax figures are federal income tax (including any alternative minimum tax), the 3.8% net investment income tax and California income tax added by the sale, from the live Big Sale Tax engine: married filing jointly, 2026 federal law (IRS Rev. Proc. 2025-32) and the 2026 FTB schedule held flat for every year.
Later brackets are indexed, so later years are shown conservatively. The 6% payout rate is an illustration, not a quote. Run your own numbers in the installment sale calculator.
The catch
- You give up liquidity: no lump sum later if you need it, unless the schedule includes one.
- The payout rate is fixed when you sign. If rates rise, you do not.
- Insurer risk replaces buyer risk; it does not vanish. Check the insurer's ratings and your state's protection association limit.
- It has to be arranged before closing. A seller who already has the cash, or a failed 1031 where the intermediary released the funds, is too late.
Gray area
Does the structured part change installment sale treatment?
- Position A. It does not. A buyer who pays a third party to take over its payment duty is still making installment payments; IRC 453 and Treas. Reg. 15a.453-1 look at what the seller can get, and the seller can get only the schedule.
- Position B. A seller who negotiates the funding and the insurer is close enough to the money that an aggressive examiner could argue economic benefit, especially if the seller can name, change or collapse the arrangement.
What both sides agree on: No control is the line. Sign before closing, no right to accelerate, pledge or sell, and keep the assignment company as the obligor, and the case for 453 is strong.
Marketing claims vs the Code
- Position A. Insurer brochures present the structure as a way to defer capital gains tax with no downside.
- Position B. The Code defers; it does not forgive. The tax on every dollar of gain is still due as it arrives, interest is taxed as ordinary income each year, and anything left at death is IRD with no step-up.
What both sides agree on: It is a timing tool. Its value is the growth on the deferred tax and the chance to land payments in lower brackets.
Compare it head to head: structured installment sale vs 1031 exchange, deferred sales trust vs installment sale, 1031 vs installment sale.
Related guides: estate tax exemption 2026, ILIT after selling property, selling a business before retirement.
Frequently asked questions
Is a structured installment sale legal?
Yes. It is an installment sale under IRC 453 with a third party making the payments. The tax result depends on the seller having no right to the cash, so it must be set up before closing.
Is a structured installment sale the same as a structured settlement?
No. They use the same assignment-and-annuity mechanics, but a structured settlement pays injury damages that IRC 104 and 130 exclude from income. Sale payments are taxable as gain and interest under IRC 453.
What is the minimum sale size?
There is no tax-law minimum. Assignment companies commonly want $100,000 or more of deferred amount. Above $5,000,000 of deferred notes at year end, the IRC 453A interest charge starts.
Can I sell my payments later?
The arrangement only works if you cannot. A right to sell, pledge or accelerate the payments gives you economic benefit, and borrowing against them counts as a payment (IRC 453A(d)).
What if the insurer fails?
The assignment company and the insurer backing it are the obligors. If the insurer fails, state life and health insurance protection associations cover annuity values up to a limit, often $250,000 per person, that varies by state. Large sales are sometimes split across insurers.
Structured installment sale vs deferred sales trust?
Both rely on IRC 453. In a deferred sales trust a trust buys the asset and invests the proceeds, so payments depend on how the trust's investments do and on the trust being respected. A structured sale pays a fixed schedule backed by an insurer. See the side-by-side.
Sources
- IRC 453, installment method, including 453(f)(6) and 453(i) (Cornell LII)
- Temp. Treas. Reg. 15a.453-1, what counts as a payment (eCFR)
- Treas. Reg. 1.453-12, unrecaptured Section 1250 gain reported first (eCFR)
- Treas. Reg. 1.451-2, constructive receipt (eCFR)
- IRC 453A, interest charge and pledge rule (Cornell LII)
- IRC 130, qualified assignments (Cornell LII)
- IRC 691, income in respect of a decedent (Cornell LII)
- IRC 1014, basis of property acquired from a decedent (Cornell LII)
- IRC 1411, net investment income tax (Cornell LII)
- IRS Publication 537, Installment Sales
- IRS Form 6252, Installment Sale Income (form and instructions)
- IRS Rev. Proc. 2025-32, 2026 inflation adjustments
- California FTB, tax calculator, tables and rates
Links checked October 30, 2026.
Hans Goldstein is an Enrolled Agent, admitted to practice before the Internal Revenue Service. Not affiliated with or endorsed by the IRS. General education, not tax or legal advice for your situation.
Insurance products offered through Goldstein & Co. LLC dba Goldstein Insurance Services, CA license 4273294. If you implement a structured installment sale through that business, Hans is paid a commission by the insurer; it is built into the payout rate. See the disclosures.
Also free: the book Same Sale, Different Tax, the same $1,000,000 gain taxed ten ways. Want it run on your sale? Book a free scope call to see whether the Big Sale Tax Analysis is worth it.
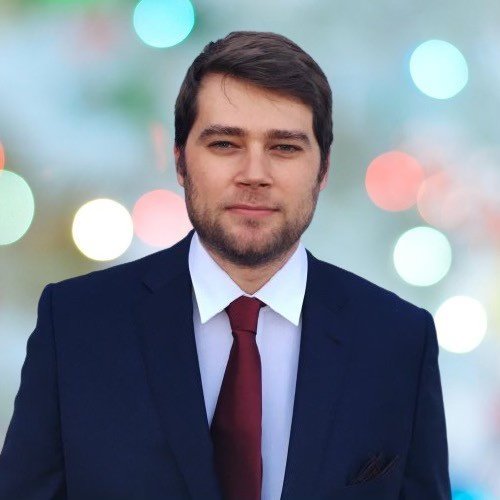
Who you will talk to
Hans Goldstein · Sacramento, California
Hans Goldstein: Tax & Exit Planning, an independent practice. Enrolled Agent, admitted to practice before the Internal Revenue Service. CA Insurance License #4273294, NPN 20602398.
- What happens first
- You fill in the short form for a free scope call, about 5 minutes. Hans reviews every one personally and replies within 1 business day. If it is a fit, you get a link to book the call.
- The scope call
- Fifteen minutes, free: price, timeline, what you are selling and what the money is for. Scope means you hear whether the analysis is worth it for your sale.
- What you get
- A written side-by-side comparison of your cash-sale baseline against every path that fits, year-by-year numbers, a written recommendation, and a review meeting with you and, if you like, your CPA and attorney.
- What it costs
- The scope call is free. The Big Sale Tax Analysis is $5,000 per household per transaction, only if you decide it is worth it. No retainer, no hourly billing, no obligation to use any strategy.
- How Hans is paid
- The $5,000 fee pays for analysis only and is not reduced or credited if you buy anything. You are never required to buy anything. No referral fees are paid to or received from brokers, CPAs or attorneys. Hans is also a licensed insurance producer with a separately owned insurance business. That business is not part of this engagement, and the analysis does not recommend insurance products. If you later choose an installment sale funded through an insurance company, that company pays Hans a commission through his separate insurance business. He may be compensated by that business if you use an insurance-funded installment sale. Hans is an Enrolled Agent (EA), admitted to practice before the Internal Revenue Service. He is not a CPA, attorney or registered investment adviser; the analysis models tax effects and does not recommend specific securities. Read the disclosures.
Book a free scope call or call 213-340-2018. Hans answers or calls back the same business day.
See it on your sale.
Send the expected price, basis and closing date. On a free scope call we compare cash, a seller note, a structured installment sale and a 1031 side by side.
Prefer email? Request the analysis by email.
You talk to Hans Goldstein. Enrolled Agent, admitted to practice before the IRS.