Structured installment sale vs seller note: two kinds of installment sales.
Both spread the gain under Section 453. The difference is who pays you, and whether you have to be the bank.
By Hans Goldstein (Enrolled Agent, admitted to practice before the IRS) · Updated
Both use Section 453 of the tax code, so the gain is taxed as you are paid instead of all in year one. The difference is who pays you, and whether you have to be the bank. Rules are 2026 federal law, checked October 15, 2026.
Side by side
Seller-carried installment sale
- The buyer puts a little down and signs a note to you.
- You are the bank. If the buyer stops paying, you foreclose to get the property back.
- Your income depends on the buyer's credit and the property holding its value.
- Fewer buyers can close, because they need you to say yes to their terms.
- Tax is spread over the payment years.
Structured installment sale
- The buyer pays in full at closing, cash or a normal loan.
- At escrow, the sale money goes to a highly rated insurance company that pays you on the schedule you pick.
- No note from the buyer, no foreclosure risk, no landlord or lender role.
- More buyers can close, because the seller can take a lower price and still net more.
- Tax is spread over the payment years.
- Payments are fixed once set and can't be sped up, and they depend on the insurance company's strength.
Run the math
Change the numbers. The tax on both kinds of installment sale is always the same, because the IRS taxes the gain as it arrives in both cases. This estimate runs in your browser and sends nothing anywhere.
Married filing jointly, federal only, 2026 brackets. Example figures, not your numbers.
What is actually different
| Seller-carried | Structured | |
|---|---|---|
| Tax treatment | Section 453 installment method | Section 453 installment method |
| Buyer pays at closing | A down payment | The full price |
| Who pays you after closing | The buyer | An insurance company |
| If payments stop | You foreclose and take the property back | No buyer note to default on |
| Buyer pool | Only buyers you will lend to | Any buyer who can close |
| Trade-off | Buyer credit and property risk | Fixed schedule, insurer strength |
| Listing broker | Paid at closing | Paid at closing, in full |
| When it must be set up | Before closing | Before closing. Once funds reach the seller, it is too late. |
Not sure which fits? See big sale options: what you want, what fits and the risk. If you are retiring with old losses, read stuck losses when you retire, because spreading the gain also spreads the release of suspended passive losses (IRC 469(g)(3)). The full rules are on the installment sale guide.
2026 federal long-term capital gains brackets, married filing jointly: 0% to $98,900, 15% to $613,700, 20% above (IRS Rev. Proc. 2025-32, checked October 15, 2026). Net investment income tax 3.8% above $250,000 of modified AGI (IRC Sec. 1411, not indexed).
State tax, depreciation recapture, interest on payments and the time value of money are not shown. Hans Goldstein is an Enrolled Agent, admitted to practice before the Internal Revenue Service. Not affiliated with or endorsed by the IRS.
General education, not tax or legal advice for your situation. Figures are illustrations only. Insurance products offered through Goldstein & Co. LLC dba Goldstein Insurance Services, CA license 4273294.
Frequently asked questions
What is the difference between a seller-carried and a structured installment sale?
Both spread the gain under Section 453. In a seller-carried sale the buyer owes you, so you take the buyer's credit and the property risk. In a structured installment sale the buyer pays in full at closing and an insurance company pays you on a fixed schedule, so the risk becomes the insurer's strength and the schedule cannot be sped up.
Is the tax different between the two?
No. Both use the Section 453 installment method, so the same gain is reported in the same years. Interest, depreciation recapture and state tax are separate and are not shown in the calculator.
When must a structured installment sale be set up?
Before closing. Once the sale funds reach the seller, it is too late.
Hans Goldstein is an Enrolled Agent, admitted to practice before the Internal Revenue Service. Not affiliated with or endorsed by the IRS. General education, not tax or legal advice for your situation.
Also free: the book Same Sale, Different Tax, the same $1,000,000 gain taxed ten ways. Want it run on your sale? Book a free scope call to see whether the Big Sale Tax Analysis is worth it.
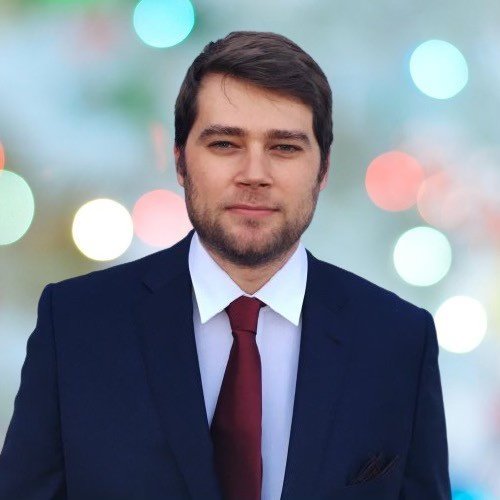
Who you will talk to
Hans Goldstein · Sacramento, California
Hans Goldstein: Tax & Exit Planning, an independent practice. Enrolled Agent, admitted to practice before the Internal Revenue Service. CA Insurance License #4273294, NPN 20602398.
- What happens first
- You fill in the short form for a free scope call, about 5 minutes. Hans reviews every one personally and replies within 1 business day. If it is a fit, you get a link to book the call.
- The scope call
- Fifteen minutes, free: price, timeline, what you are selling and what the money is for. Scope means you hear whether the analysis is worth it for your sale.
- What you get
- A written side-by-side comparison of your cash-sale baseline against every path that fits, year-by-year numbers, a written recommendation, and a review meeting with you and, if you like, your CPA and attorney.
- What it costs
- The scope call is free. The Big Sale Tax Analysis is $5,000 per household per transaction, only if you decide it is worth it. No retainer, no hourly billing, no obligation to use any strategy.
- How Hans is paid
- The $5,000 fee pays for analysis only and is not reduced or credited if you buy anything. You are never required to buy anything. No referral fees are paid to or received from brokers, CPAs or attorneys. Hans is also a licensed insurance producer with a separately owned insurance business. That business is not part of this engagement, and the analysis does not recommend insurance products. If you later choose an installment sale funded through an insurance company, that company pays Hans a commission through his separate insurance business. He may be compensated by that business if you use an insurance-funded installment sale. Hans is an Enrolled Agent (EA), admitted to practice before the Internal Revenue Service. He is not a CPA, attorney or registered investment adviser; the analysis models tax effects and does not recommend specific securities. Read the disclosures.
Book a free scope call or call 213-340-2018. Hans answers or calls back the same business day.
Know your number before you sign.
Start with a free scope call: a short call to see whether the Big Sale Tax Analysis is worth it for your sale. No obligation.
Prefer email? Request the analysis by email.
You talk to Hans Goldstein. Enrolled Agent, admitted to practice before the IRS.