Media and press kit
Bio, headshot, approved quotes and free state tax data for reporters, hosts and editors.
Hans Goldstein, Enrolled Agent ·
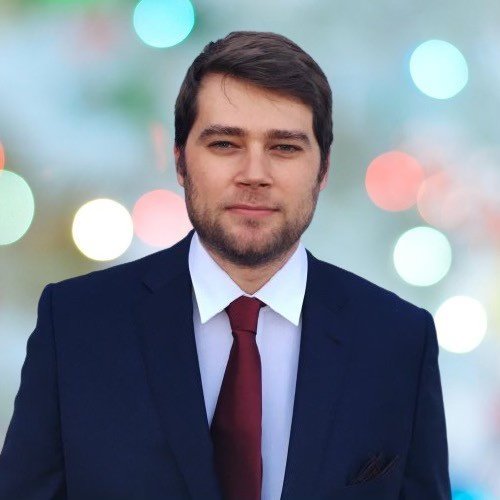
- Name
- Hans Goldstein, EA
- Credential
- Enrolled Agent, admitted to practice before the Internal Revenue Service
- Practice
- Hans Goldstein: Tax & Exit Planning (Big Sale Tax)
- Based in
- Sacramento, California
- [email protected]
- Headshot
- Download, 500 by 500 JPG
Bio
Short bio (52 words):
Hans Goldstein is an Enrolled Agent, admitted to practice before the Internal Revenue Service, and runs Hans Goldstein: Tax & Exit Planning, the practice behind Big Sale Tax. He works out what sellers of businesses, farms and rental property keep after tax, and publishes the state-by-state numbers free, with sources and dates.
Full bio:
Hans Goldstein is an Enrolled Agent (EA), admitted to practice before the Internal Revenue Service. He is not a CPA or an attorney. He runs Hans Goldstein: Tax & Exit Planning, an independent practice built around one moment: the months before a big sale closes.
Brokers started calling him the big sale tax guy because he shows a seller each way to structure the sale in dollars, side by side: cash at closing, a seller-carried note under Section 453, a 1031 exchange, an Opportunity Zone and the rest.
He grew up a farm kid in Wisconsin, milking cows at eleven. When his parents' CPA could not give a straight answer on how the home sale exclusion treats a mixed-use farm, he went to work on the answer himself.
Today he publishes the Exit Tax Map, which shows what a business sale costs in state tax in all 50 states and DC, and a free book, Same Sale, Different Tax. He is based in Los Angeles.
Please describe Hans as an Enrolled Agent, admitted to practice before the IRS. He is not a CPA or an attorney, and Big Sale Tax is not affiliated with or endorsed by the IRS.
What he covers
- What a business sale costs in state tax. All 50 states and DC on the same $10 million sale, so a reporter can name the spread. See the page.
- What a seller keeps after federal, 3.8% and state tax. Net proceeds by state, with an optional multi-year payment comparison. See the page.
- Installment sales and seller-carried notes. Section 453, the two kinds of installment sale, and when spreading the gain lowers the bill. See the page.
- Selling a farm, ranch or family business. Basis, depreciation recapture, the home sale exclusion on mixed-use property, and timing. See the page.
- Tax tools sellers ask about. Honest write-ups of 1031 exchanges, Opportunity Zones, charitable trusts, Deferred Sales Trusts and more, benefits and trade-offs on the same page. See the page.
- Moving states or countries before a sale. How residency changes who taxes the gain, with Norway's wealth tax as the worked comparison.
Five quotes you can use
These five quotes are approved for use as written. Each restates a figure from the Exit Tax Map, computed October 18, 2026 for a single filer selling the assets of an in-state operating business held over five years, all long-term gain, no other income. The numbers are sourced and dated on the Map.
“The federal bill on a $10 million business sale is the same $2,334,488 in every state. Where the business sits decides the rest: a California seller pays $1,300,185 in state tax and a Texas seller pays $0.”
Quote 1 of 5. Hans Goldstein, EA.
“A $3 million sale paid in five yearly payments leaves the seller $182,048 better off in Texas and $272,897 better off in California than one payment at closing, because each year's gain is taxed in lower brackets.”
Quote 2 of 5. Hans Goldstein, EA.
“Most states tax a business sale as plain capital gain, but New Mexico, Ohio and Oklahoma have rules written for selling an in-state business, and Oklahoma's can bring the state tax to $0.”
Quote 3 of 5. Hans Goldstein, EA.
“Washington has no wage tax, yet a $10 million sale there owes $933,478 in state tax, 7th highest of 51, because the 7% capital gains tax adds 2.9% above $1 million of gain.”
Quote 4 of 5. Hans Goldstein, EA.
“This is education, not advice. The table assumes one filer, one asset sale and no other income, so a real sale lands somewhere different once its own facts are in.”
Quote 5 of 5. Hans Goldstein, EA.
Data you can cite
Free to use with a link back. Suggested credit: Source: Big Sale Tax, Exit Tax Map, bigsaletax.com/data/exit-tax-map-by-state/
| File | What it is |
|---|---|
| Exit Tax Map, CSV | State tax on a business sale, all 50 states and DC, single filer, 2026 law, each rule dated and sourced. |
| Exit Tax Map, JSON | Same table with the rule text and source URLs. |
| What You Keep ranking, CSV | What a seller keeps from a $3 million business sale in each state, one payment against five yearly payments. |
| Capital gains tax by state, CSV | Top state rate on long-term gains, 2026. |
| Capital gains tax statistics, CSV | Federal brackets, the 3.8% tax and state rules in one table. |
| Installment sale thresholds, CSV | The dollar lines that change how an installment sale is taxed in 2026. |
| Applicable federal rates, monthly, CSV | Monthly AFR history, 2023 to 2026. |
| IRS underpayment rate, quarterly, CSV | Quarterly IRS interest rate on underpayments. |
Method and press kit for the Exit Tax Map: press kit and changelog. Free book: Same Sale, Different Tax.
Book Hans
For interviews, podcasts, bylined pieces and expert quotes, email [email protected] with the outlet, the topic and your deadline, or book a free scope call.
As seen in
Hans Goldstein is an Enrolled Agent, admitted to practice before the Internal Revenue Service. Not affiliated with or endorsed by the IRS. He is not a CPA or attorney. Education only, not tax or legal advice for your situation.